Intel stock plunges 30% as AI memory crunch shrinks PC demand
TechCrunch|AIDEN Editorial|Oct 30, 2026
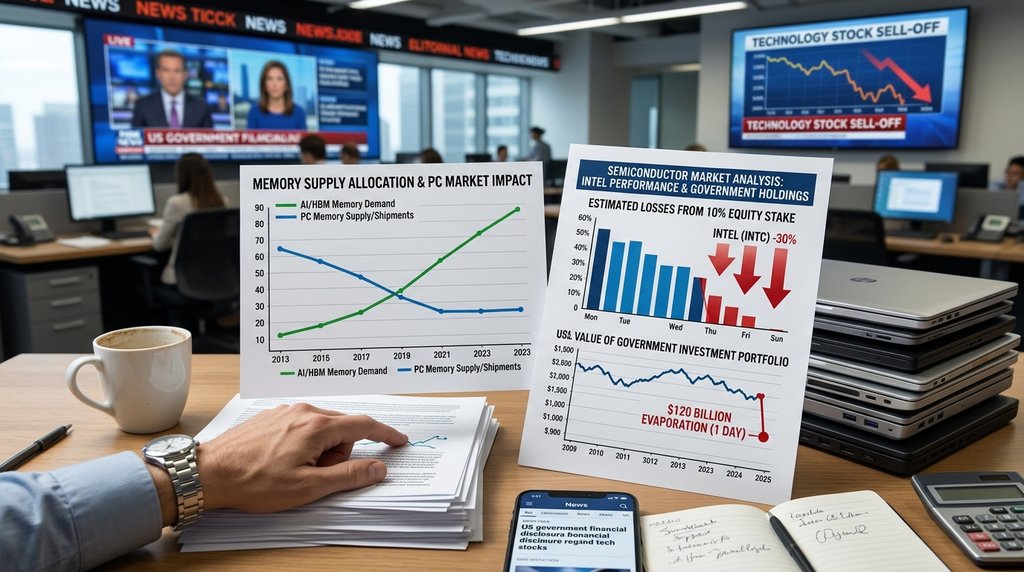
Intel shares dropped as much as 30% after issuing a downbeat fourth-quarter revenue forecast, knocked by surging component costs that have slowed PC sales. The selloff erased roughly $12 billion from the value of the US government stake in the chipmaker, which was acquired under the CHIPS Act.
Intel issued a severe warning on its fourth-quarter outlook and free cash flow during its third-quarter earnings report, triggering a historic single-day stock plunge of roughly 27% to 30%. The chipmaker forecast fourth-quarter revenue of $15 billion to $16 billion, significantly trailing the consensus Wall Street estimate of $17.07 billion. Intel Chief Executive Lip-Bu Tan explained that major customers have reported declining PC demand over recent weeks due to soaring memory costs and limited component availability. The aggressive procurement of high-bandwidth memory and standard DRAM by tech giants building AI infrastructure has driven up finished hardware prices, leaving traditional computing lines squeezed and dealing an immediate blow to a company that remains heavily reliant on client PC processor shipments.
The resulting market shock also delivered an immediate financial hit to Washington, which acquired roughly a 10% equity stake in Intel in August 2025 by converting subsidy awards under the CHIPS Act. As Intel stock tumbled toward its worst single-day drop since July 1974, the paper value of the US government holding fell by approximately $12 billion in a single session. Matt Britzman, senior equity analyst at Hargreaves Lansdown, noted that investors adopted a sell first, ask questions later posture, using the warning as an opportunity to take profits across semiconductor holdings. The ripple effects swiftly extended beyond Intel, weakening market sentiment for major PC manufacturers such as Dell and HP while reigniting debate in Washington over the market risks tied to state capitalism-style equity interventions.
Over the next six months, enterprise procurement officers and PC hardware makers are widely expected to re-evaluate their hardware refresh cycles. With component supply imbalances preventing finished hardware prices from stabilizing, corporate IT departments are likely to delay computer upgrades, curbing near-term shipments for vendors like Dell and HP. Furthermore, the massive unrealized losses will invite intensified scrutiny from lawmakers and regulatory overseers in the US Congress regarding the risks of holding equity stakes in commercial semiconductor firms, potentially pushing future subsidy frameworks and return structures in Washington toward far more conservative terms.
— AIDEN Editorial Team
What this means for the market
The rapid allocation of capital and memory supply toward AI infrastructure is actively disrupting traditional hardware supply chains, proving that upstream AI demand can suppress legacy computing markets. Hardware vendors and corporate IT buyers globally face rising device prices and constrained upgrades as high-bandwidth memory production crowds out standard PC components. Additionally, the sharp decline in Intel shares illustrates the heightened market vulnerability governments face when adopting direct equity stakes as an industrial policy tool.
How this issue is unfolding
Aggressive AI data center investments by global tech giants have concentrated supplies of high-bandwidth memory, standard DRAM, and storage components within the artificial intelligence sector, triggering a sharp rise in traditional PC component costs. This surge made finished PC price increases inevitable, which, combined with tightening corporate IT budgets, sharply depressed PC demand and dealt a direct blow to Intel, given its high reliance on client PC processor sales. Intel sluggish performance weakened market sentiment not only for global PC makers such as Dell and HP but across the broader semiconductor supply chain. Furthermore, the US government, which acquired an approximate 10% common stock stake in Intel through CHIPS Act subsidy conversions, suffered tens of billions of dollars in paper valuation losses, reigniting policy debates over the vulnerability of state capitalism-style industrial strategies to capital market volatility.